South Seattle Self-Employed Workers: Compare 2027 Health Coverage Before the Premium Surprise |
A Georgetown-to-Columbia City guide to comparing total insurance costs while Washington's 2027 open enrollment is underway. |
A freelancer's budget can look healthy until a medical bill or an unexpected premium increase arrives. For self-employed people in Columbia City, Georgetown and Rainier Valley, insurance belongs in the business and household cash-flow plan—not in the category of paperwork to handle later.
Washington Healthplanfinder says open enrollment for 2027 coverage is underway. Its current guidance says to select a plan by December 31, 2026 for coverage beginning January 1, 2027, or by January 15, 2027 for February 1 coverage. These are plan-selection dates, not a guarantee that every application will be approved instantly.
Begin with the total annual cost. Multiply the monthly premium by twelve, then consider the deductible, copayments, coinsurance, prescription coverage and out-of-pocket maximum. A low monthly premium may be costly for someone who uses regular specialist care or expensive prescriptions.
Compare provider networks before focusing on the premium alone. Check whether your regular clinic, hospital and prescriptions are covered under the exact 2027 plan, not just the insurance company's name. Provider networks and formularies can change from one plan year to another.
Self-employed income may fluctuate. Enter a reasonable estimate based on expected income, keep supporting records, and update your marketplace application if your circumstances change. Eligibility for premium assistance can depend on income and household information, so an inaccurate estimate may create complications at tax time.
Budget for a slow month. If an independent contractor expects uneven cash flow, set aside a portion of stronger-month receipts for recurring premiums. Insurance is not a substitute for an emergency fund, but it can reduce the risk that one health event drains that fund.
Free enrollment assistance is available through Washington Healthplanfinder's navigators and customer-service channels. A navigator can help explain the application process; choosing between plans still requires checking your family's actual medical and financial needs.
Take thirty minutes this week to compare at least two plans on the same assumptions: the same doctors, medicines, expected visits and worst-case out-of-pocket costs. Keep a screenshot or notes of the final comparison before choosing.
Official marketplace: Washington Healthplanfinder — https://www.wahealthplanfinder.org/ . Independent educational coverage; no insurance referral commission or affiliate relationship is involved. |
More from WealthWire South End
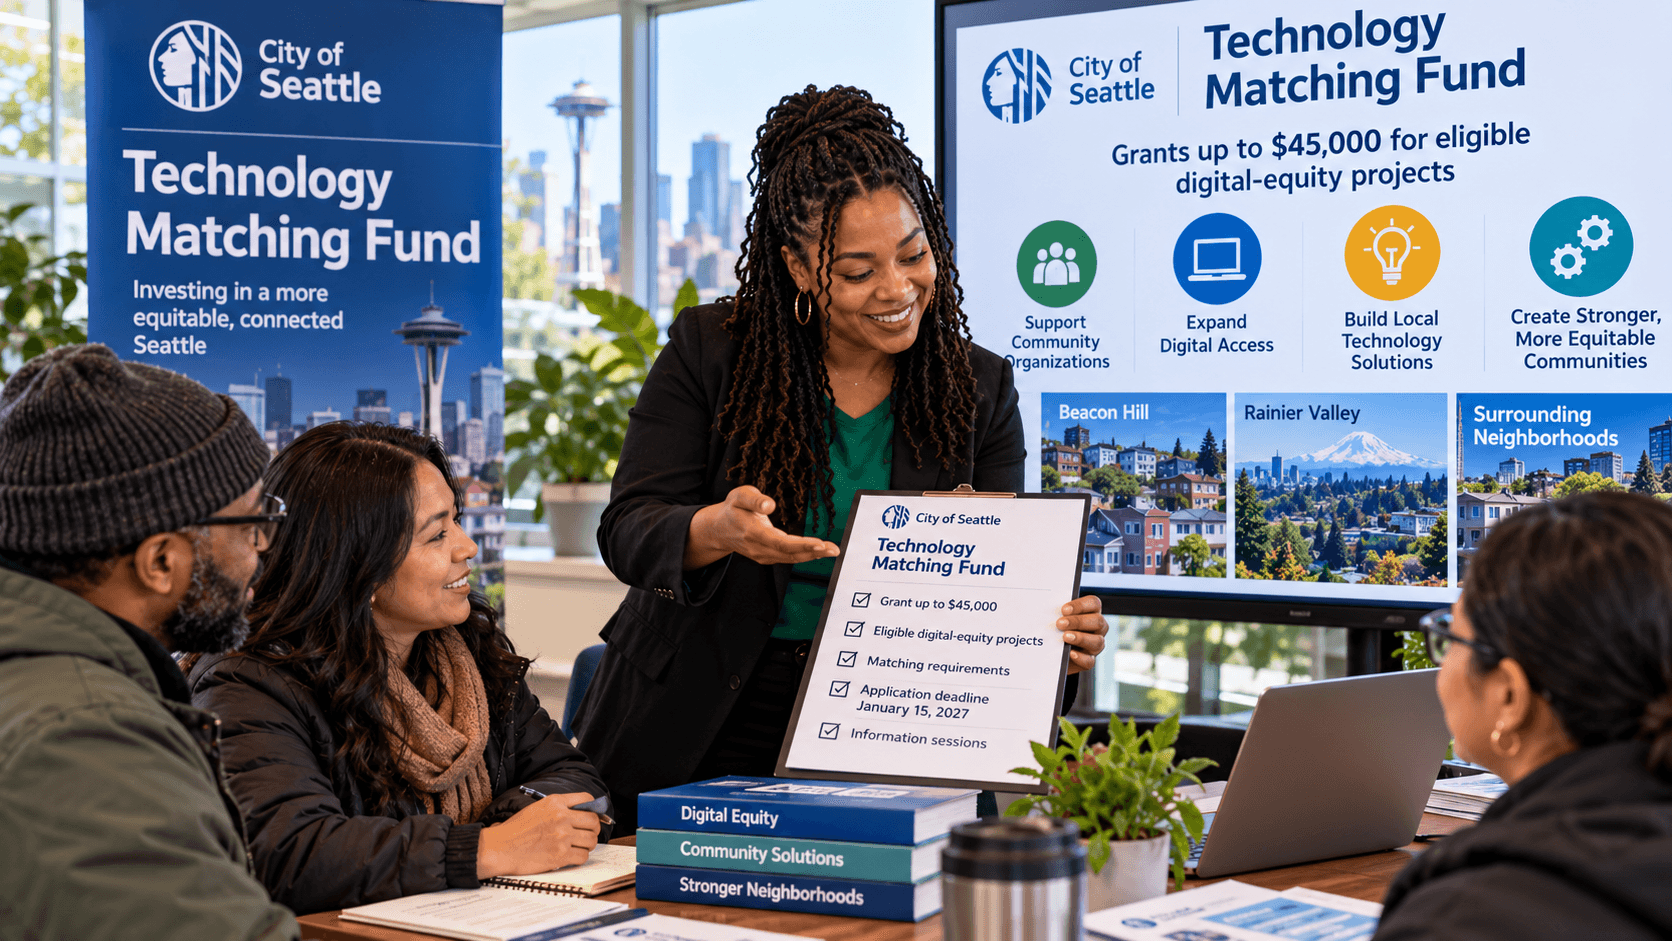
South Seattle Digital Equity Grants: Up to $45,000 Available
Digital equity grants of up to $45,000 are open for eligible South Seattle groups. Check the October 27 session and January 15 deadline.
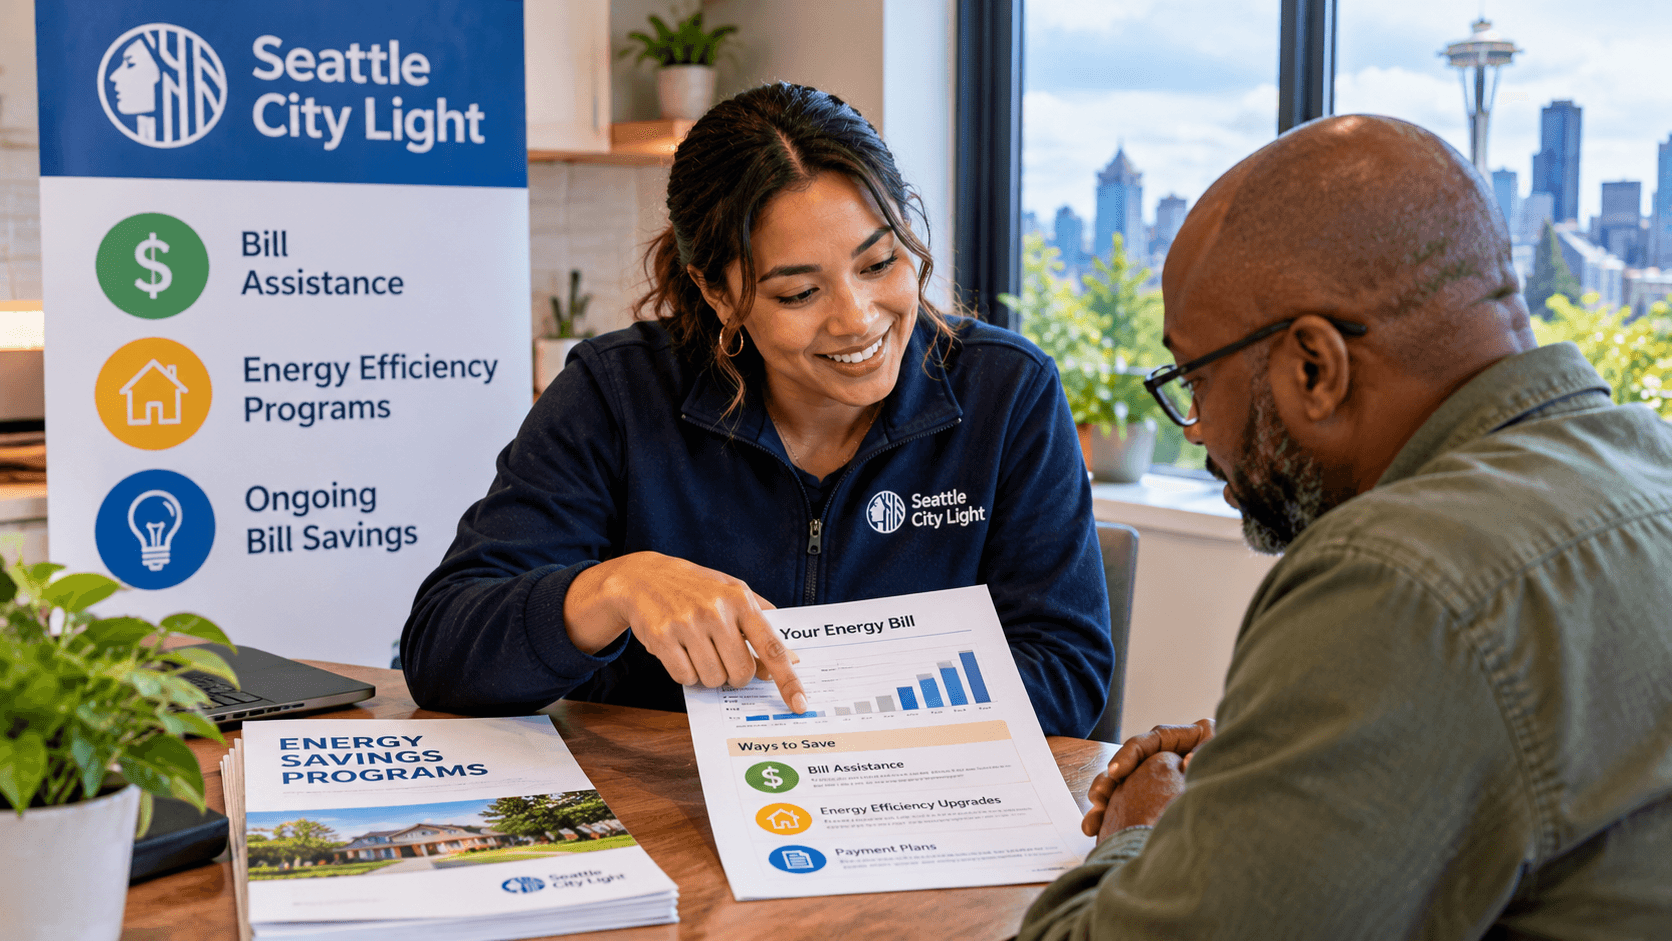
South Seattle Utility Discounts: Check Eligibility Before Winter
utility discount program: Seattle City Light customers may qualify for substantial ongoing bill reductions and emergency help
South Seattle Businesses: Free Consulting Beyond the Usual Advice
small business consulting: A Seattle program offers eligible small businesses practical accounting, marketing and loan-readiness support
Rainier Valley Rainy-Season Readiness Starts at the Storm Drain
storm drain care: Seattle's Adopt-a-Drain program gives neighbors a practical way to reduce localized flooding risks
0 Comments
Join the conversation
Be the first to comment
Share your thoughts above.